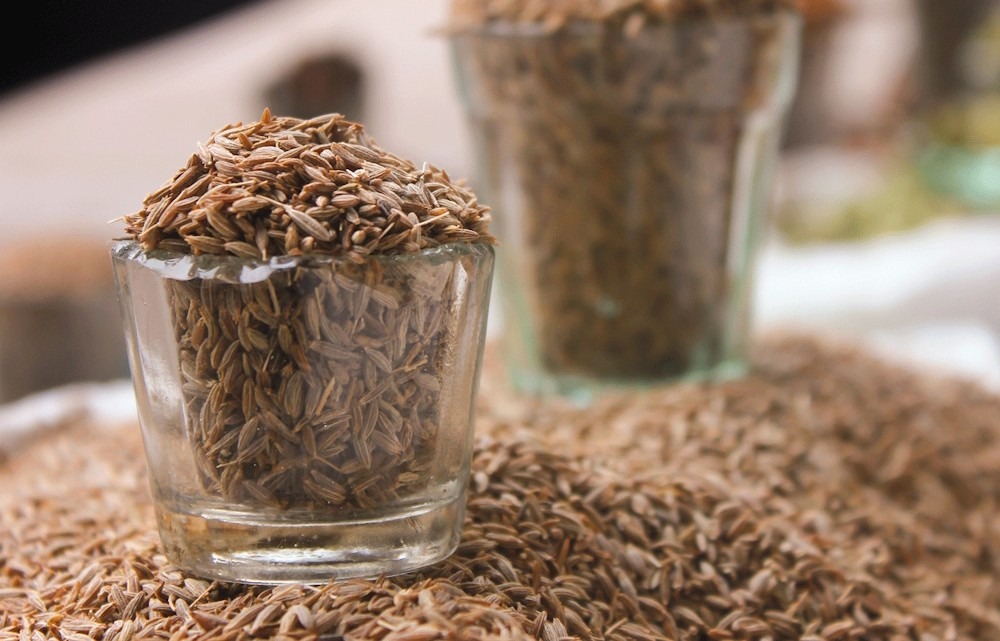
Despite constant overall physical crop supply, Jeera settled 1.67% higher at Rs 22,540 amid rapidly narrowing availability of premium-quality bold seeds, with export-grade high-purity types becoming increasingly scarce. Daily arrivals at major markets like Unjha and Rajasthan have begun to decrease markedly, as European and North American buyers have resumed their activities, concentrating on residue-compliant and high-specification lots. Nevertheless, geopolitical instability in the Middle East persists in disrupting logistics and exerting pressure on demand from conventional purchasers.
Upside potential appears constrained as farmers are currently liquidating inventories to enhance cash flow in anticipation of the upcoming season, while favourable weather conditions have facilitated the earlier completion of harvesting and drying processes. NCDEX warehouse stocks have shown a consistent increase, which has diminished the urgency among traders. Meanwhile, large industrial spice grinders are engaging in hand-to-mouth purchasing rather than pursuing aggressive bulk procurement. Blight outbreaks in critical regions of Gujarat have negatively impacted both crop quality and the quantities available for harvest. Meanwhile, enhanced production forecasts in Turkey and Syria are constraining export premiums for Indian agricultural products. Domestic processors and stockists are likewise diminishing their forward coverage.
Current estimates indicate that India’s jeera production is projected to be between 90 and 92 lakh bags, a decline from last year’s figure of 1.10 crore bags. Specifically, production in Gujarat is estimated to range from 42 to 45 lakh bags, while Rajasthan’s production is anticipated to be between 48 and 50 lakh bags. Overseas production is projected to be between 70,000 and 80,000 tonnes in China, 9,000 to 10,000 tonnes in Syria, 10,000 to 11,000 tonnes in Turkey, and 10,000 to 12,000 tonnes in Afghanistan. India’s jeera exports experienced a significant decline of 32% year-on-year, totalling 9,318 tonnes in July 2026. Furthermore, cumulative exports for the period from April to July decreased by 27%, amounting to 53,462 tonnes.
Singapore’s exports experienced a remarkable increase of 889%, reaching 2,842 tonnes, while Libya saw a substantial rise of 450% to 341 tonnes. In contrast, exports from China faced a significant decline of 88%, totalling 710 tonnes. In Unjha, spot prices concluded at Rs 22,269.55, reflecting an increase of 0.37%. From a technical perspective, jeera is experiencing short covering, as evidenced by a 17.71% decline in open interest to 5,145, accompanied by a price increase of Rs 370. Support is positioned at Rs 22,270, and a breach beneath this level may result in a decline to Rs 22,000. On the upside, resistance is observed at Rs 22,700, while a sustained movement above this threshold could propel prices toward Rs 22,860.