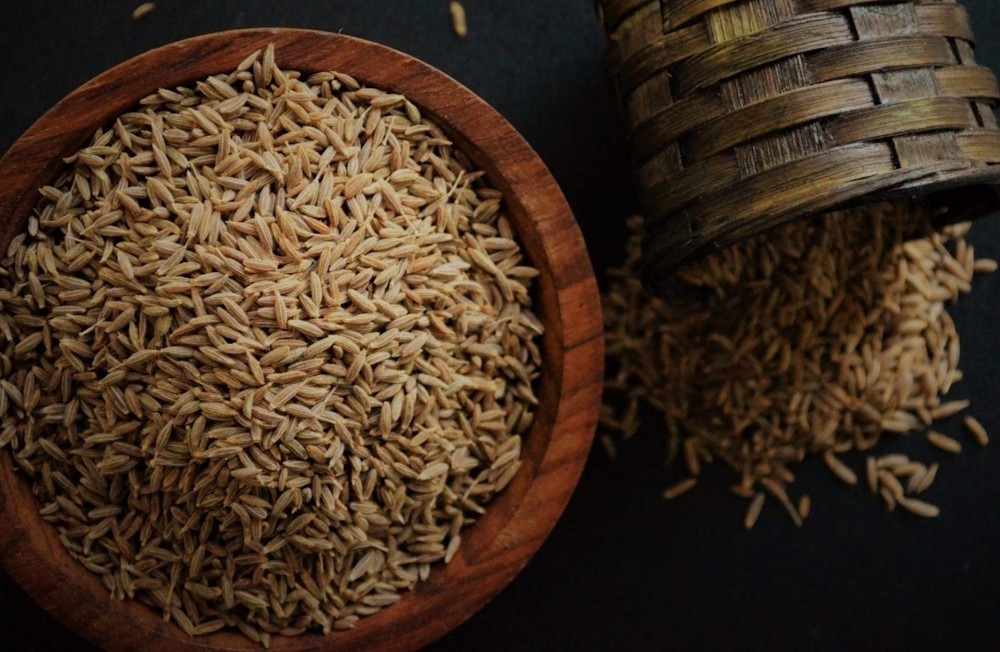
With export-grade high-purity supplies declining more quickly than overall physical availability, Jeera’s price increased by 3.24% to Rs 23,565, helped by a dramatic tightening in the supply of premium-quality bold seeds. Daily arrivals in significant markets like Unjha and Rajasthan have begun to decline, while outbreaks of blight in crucial areas of Gujarat have impacted both crop quality and the volumes available for harvest. European and North American buyers have re-entered the market for residue-compliant and high-specification lots, offering targeted export support.
However, the potential for upside appears constrained as farmers are actively liquidating inventories to meet cash needs for the upcoming season, while favourable weather conditions have expedited both harvesting and drying processes. NCDEX warehouse stocks have continued to accumulate, diminishing the urgency for immediate procurement. Consequently, large spice grinders are adopting a hand-to-mouth buying strategy instead of engaging in aggressive forward coverage. Enhanced production expectations in Turkey and Syria are exerting downward pressure on Indian export premiums. Domestic and export demand exhibits a mixed landscape, as evidenced by India’s jeera exports, which have experienced a year-on-year decline of 32% to 9,318 tonnes in July 2026. Furthermore, cumulative exports from April to July have decreased by 27%, totalling 53,462 tonnes.
Singapore’s exports experienced a remarkable increase of 889%, reaching 2,842 tonnes, while Libya saw a significant rise of 450% to 341 tonnes. In contrast, exports to China fell sharply by 88%, totalling 710 tonnes, underscoring a notable weakness in this key market. Domestic production is projected to be between 90 and 92 lakh bags this season, a decline from last year’s figure of 1.10 crore bags. In Gujarat, production is estimated at 42 to 45 lakh bags, while Rajasthan’s output is anticipated to be between 48 and 50 lakh bags. Overseas production estimates continue to hold significance, with projections for China ranging from 70,000 to 80,000 tonnes, Syria between 9,000 and 10,000 tonnes, Turkey at 10,000 to 11,000 tonnes, and Afghanistan estimated at 10,000 to 12,000 tonnes.
Unjha spot prices concluded at Rs 23,284.55, reflecting an increase of 0.57%. Technically, jeera is experiencing short covering, evidenced by a 5.74% decline in open interest to 4,533, while prices have increased by Rs 740. Support is positioned at Rs 23,110, and a sustained breach beneath this threshold may reveal Rs 22,660. On the upside, resistance is observed at Rs 23,890, with a decisive move above this threshold potentially driving prices toward Rs 24,220.