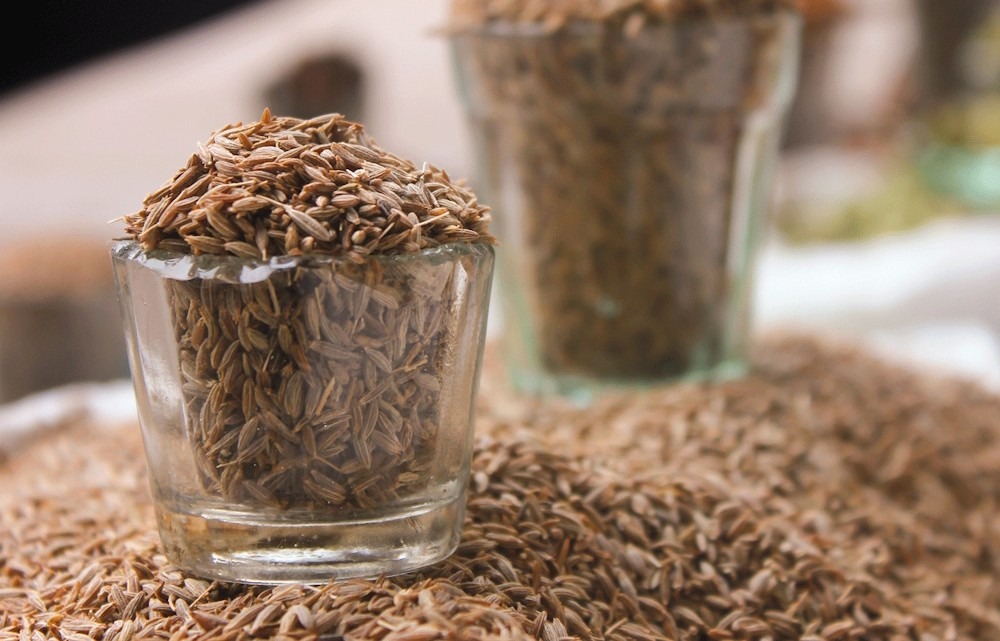
Jeera prices concluded the trading session with an increase of 0.29% at 27550 yesterday. This uptick was bolstered by heightened export demand, alongside a contraction in both domestic and global supplies. Additionally, apprehensions regarding weather patterns and restricted water availability associated with the El Niño phenomenon are raising concerns about agricultural productivity, potentially leading to reduced yields and uncertainty surrounding sowing activities in crucial cumin-producing areas such as Rajasthan, where insufficient soil moisture may impact agricultural decisions. Furthermore, the Gujarat government has designated Jamnagar, Devbhumi Dwarka, Porbandar, and Kutch as districts facing scarcity issues. With Syrian supplies remaining minimal, demand for Indian cumin seed is higher despite China beginning to cultivate its own crop.
However, upside momentum is capped by profit booking, expectations of stable-to-higher sowing acreage in Saurashtra and western Rajasthan, aggressive liquidation of stocks by farmers for immediate cash flow, faster harvesting and drying due to favourable Northwest Indian weather, and improved production prospects in secondary origins like Turkey and Syria. These factors have weighed on export premiums as domestic processors moved away from aggressive forward coverage and restricted procurement to need-based daily requirements amid a slowdown in seasonal pipeline replenishment. Fundamental estimates suggest that national cumin production for the current season is anticipated to be between 90 and 92 lakh bags, a decline from last year’s figure of 1.10 crore bags. Gujarat is expected to contribute approximately 42 to 45 lakh bags, while Rajasthan is projected to yield 48 to 50 lakh bags.
Additionally, international production forecasts indicate output of 70 to 80 thousand tonnes in China, 9 to 10 thousand tonnes in Syria, 10 to 11 thousand tonnes in Turkey, and 10 to 12 thousand tonnes in Afghanistan. In August 2026, India’s jeera exports experienced a year-on-year decline of 19.7%, totalling 11,667 tonnes, compared to 14,532 tonnes in August 2025. This reduction brought cumulative exports for the April-August period down to 65,128 tonnes from 87,558 tonnes the previous year. Notably, there were increases in shipments to the USA, which rose by 16.5% to 1,517 tonnes, Singapore, which surged by 1,442% to 633 tonnes, and Mexico, which increased by 149.5% to 373 tonnes. These gains, however, were overshadowed by significant declines in shipments to the UAE, which fell by 81.6% to 453 tonnes, and Bangladesh, which decreased by 45.8% to 569 tonnes.
Over the broader annual period from September 2025 to August 2026, total exports declined by 17.4% to 174,479 tonnes, with Bangladesh remaining the largest destination at 23,541 tonnes, followed by the UAE at 17,383 tonnes and the USA at 16,998 tonnes. In the physical market, spot prices at the benchmark Unjha APMC market remained subdued, experiencing a marginal increase of 0.01% to settle at Rs 27181.1, as processors and millers exhibited resistance to elevated spot quotes. From a technical perspective, the market is experiencing short covering, evidenced by a decline in open interest of 18.25%, which has settled at 4449. Concurrently, prices have increased by Rs 80, with immediate support for jeera identified at Rs 27340. A breach below this level could lead to a test of Rs 27130. On the upside, resistance is anticipated at Rs 27810, and a movement above this threshold may result in prices testing Rs 28070.